How to Build an Emergency Fund When Money Is Tight
Building emergency savings may feel impossible when every paycheck is already committed. Here is a realistic way to start with a small goal and make steady progress.
By Michael “Mike” Torres | Payday & Purpose
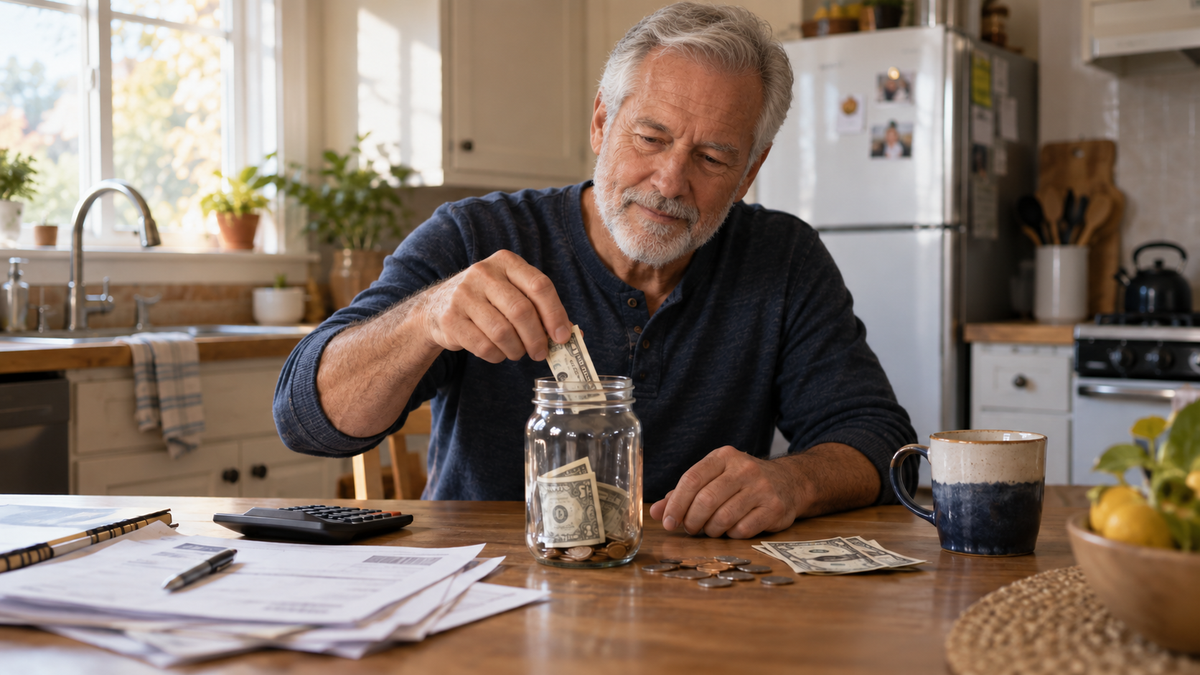
You do not need hundreds of extra dollars every month to begin building financial protection. You need a realistic first goal, a place to keep the money and a system you can repeat.
Most advice about emergency funds begins with the same intimidating recommendation: save enough to cover three to six months of expenses.
That may be a worthwhile long-term goal, but it is not especially helpful when your paycheck is already spoken for. If you are struggling to cover groceries, housing, utilities, insurance and debt payments, saving thousands of dollars can feel impossible.
So forget thousands for the moment.
Your first emergency fund does not need to replace your income for six months. It needs to keep one ordinary setback from becoming a financial crisis. Here is how to start building that protection—even when money is tight.
1. Begin with a goal you can actually reach
Start with $250 or $500, not six months of expenses.
That amount will not solve every emergency, but it could cover a minor car repair, an unexpected prescription, an insurance deductible or part of an urgent household expense.
A smaller target also gives you a finish line you can see. Reaching $250 creates evidence that you can save. After that, you can work toward $500, then $1,000 and eventually one month of essential expenses.
Progress is easier when the next goal feels possible.
2. Decide what counts as an emergency
An emergency fund is for expenses that are:
- Necessary
- Unexpected
- Urgent
- Not covered by your regular income
A broken water heater may qualify. A sale on a new television does not. A necessary car repair could qualify. Christmas gifts should eventually become a planned expense because Christmas arrives at the same time every year.
Defining an emergency before one happens reduces the temptation to use the money whenever your checking balance runs low. A family member’s crisis can make that boundary harder. Before using your cushion for someone else, read Should You Help Family Financially When You’re Struggling Too?
3. Keep the money separate
Open a separate savings account that does not charge a monthly maintenance fee or require a balance you cannot maintain.
The account should be accessible when you truly need it, but not so convenient that you spend from it routinely. Keeping emergency savings outside your everyday checking account also prevents the balance from looking like money available for normal purchases.
Do not invest your starter emergency fund in stocks or anything that could lose value shortly before you need it. The purpose of this money is safety and access—not maximum growth.
4. Find your smallest dependable amount
Review one month of spending and look for an amount you can save consistently, even during a difficult month.
That might be $5 a week, $10 per paycheck or $25 a month. The number is less important than whether it is repeatable.
Saving $10 from every biweekly paycheck would produce $260 in one year. That may not sound dramatic, but it is considerably better than having nothing available when a tire goes flat.
Do not choose an amount so aggressive that you must transfer it back before payday. A smaller deposit that stays saved is more useful than a larger deposit that repeatedly returns to checking.
5. Make the transfer automatic
Schedule your savings transfer for the day you are paid—or ask whether your employer can divide your direct deposit between checking and savings.
Both the Consumer Financial Protection Bureau and the Federal Deposit Insurance Corporation identify automatic deposits or transfers as practical ways to build savings.
Automation removes the need to make the same decision every payday. Treat the deposit like a small bill owed to your future self.
6. Use irregular money to make larger jumps
Small recurring deposits build the habit. Occasional money can build the balance faster.
Consider saving part of:
- A tax refund
- Overtime or bonus pay
- A cash gift
- A rebate
- Income from selling unused belongings
- A month with an extra paycheck
You do not have to save the entire amount. Decide on a percentage before the money arrives—perhaps 25%—and use the rest for current needs or debt.
The IRS also allows eligible taxpayers to direct portions of a federal refund into different accounts using Form 8888. That can move part of a refund directly into savings before it is absorbed into everyday spending.
7. Cut one expense, not everything enjoyable
A budget that removes every small pleasure usually feels like punishment and may not last.
Instead, identify one recurring expense that provides less value than it costs. It might be a subscription you rarely use, frequent delivery fees or a service plan that can be reduced.
Then redirect that exact amount into savings. Canceling a $15 monthly subscription does not build an emergency fund unless the $15 is actually moved somewhere else.
You are not simply spending less. You are assigning that money a new job.
8. Create a temporary savings sprint
Choose a brief period—perhaps 30 days—and look for extra ways to reach your first goal.
During that month, you might sell unused items, accept an extra shift, prepare more meals at home or temporarily pause selected nonessential purchases.
A sprint should have a target and an ending. “I will save an extra $150 this month” is clearer than “I will never spend money on anything enjoyable again.”
Short-term intensity can help establish the fund. A modest automatic transfer can maintain it afterward.
9. Balance saving with debt payments
When expensive debt is growing, saving money while paying high interest can feel contradictory. But sending every available dollar to debt may leave you dependent on the same credit card when the next emergency occurs.
Continue making required payments, but consider establishing a small cash cushion before directing all extra money toward debt. Once the starter fund is in place, you can decide how to divide additional money between expanding savings and reducing balances.
The right balance depends on your interest rates, job stability, essential expenses and access to other resources. The goal is to stop unexpected costs from repeatedly pushing you backward.
10. Refill it without blaming yourself
Using an emergency fund for a genuine emergency does not mean you failed. It means the fund did its job.
Afterward, return to the same system and rebuild it. Review what happened and decide whether the expense was a rare surprise or something that should become part of your regular budget.
Eventually, you can expand your goal from $500 to $1,000, then toward one month of essential expenses. Longer-term protection can come later.
Start with the next dollar
Building an emergency fund while money is tight will not always feel impressive. The first deposits may look painfully small.
But the purpose is not to impress anyone. It is to create distance between an unexpected bill and a financial disaster.
Open the account. Choose the first target. Schedule the first transfer.
You do not have to solve six months of possible problems today. You only have to make the next emergency a little easier than the last one.