The Fed Can Cut Interest Rates. It Cannot Make Prices Go Back Down.
Lower interest rates may help borrowers and support jobs, but they will not restore the prices Americans remember. Here’s why inflation can slow while everyday life still feels expensive.
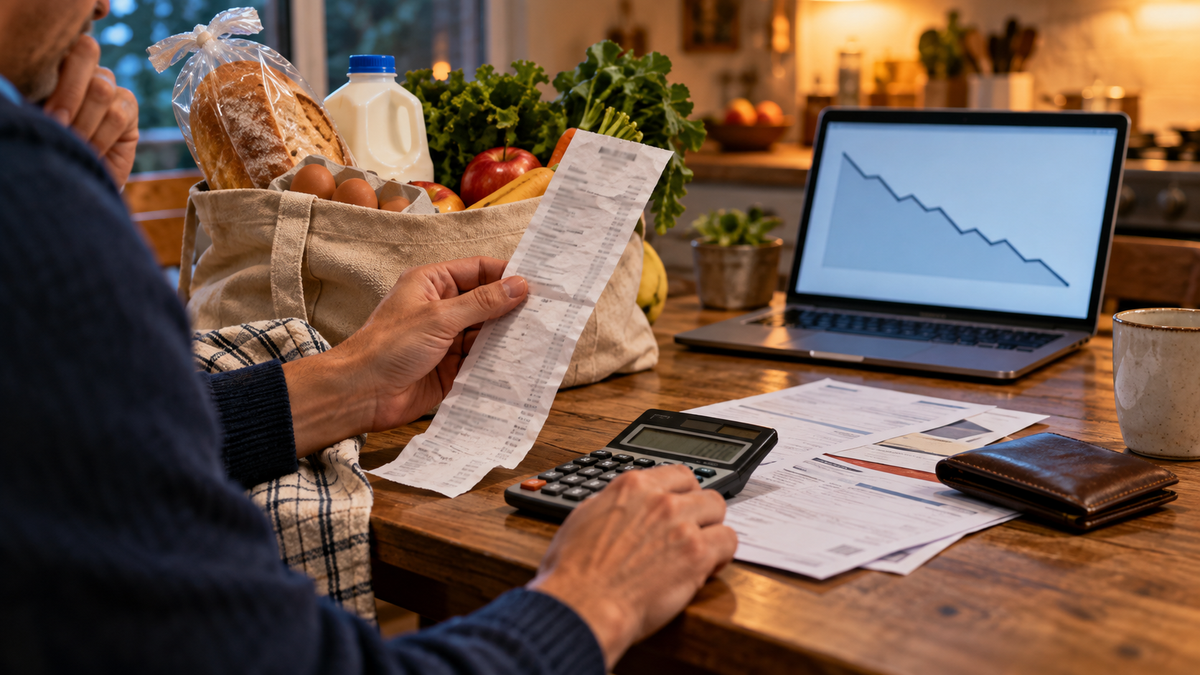
Lower interest rates can make borrowing easier and support the economy. They do not reverse years of inflation—and that is not what rate cuts are designed to do.
By Tom Mercer | The Brief
When the Federal Reserve lowers interest rates, the announcement can sound like relief is finally on the way.
Mortgages should become cheaper. Credit-card rates might ease. Businesses may borrow and hire. After years of expensive groceries, rent, insurance and nearly everything else, it is natural to expect lower rates to push everyday prices back down too.
They usually do not.
That is not because the policy failed. It is because interest rates and consumer prices are connected in a slower, less direct way than the headlines sometimes suggest.
The Federal Reserve can influence how quickly prices rise. It cannot turn back the economic clock and restore the price tags people remember from several years ago.
Slower Inflation Still Means Higher Prices
The most important distinction is between inflation and the overall price level.
Inflation measures how quickly prices are rising. If inflation falls from 7 percent to 3 percent, prices have not declined. They are still going up—just more slowly.
Think of a car easing from 70 miles per hour to 30. It is moving more slowly, but it has not gone into reverse.
The latest Consumer Price Index report illustrates the point. The Bureau of Labor Statistics said consumer prices rose 3.4 percent over the 12 months ending in August 2026. Prices increased 0.4 percent during August alone. Food was 2.7 percent more expensive than a year earlier, while shelter costs rose 3 percent.
Those percentages measure additional increases on top of the price gains households already absorbed in previous years.
For the overall price level to fall, the economy would need deflation—a broad and sustained decline in prices. That may sound appealing at the grocery store, but widespread deflation can arrive with falling wages, weaker demand, layoffs and recession. It can also make existing debts harder to repay because the dollars owed become more valuable.
That is one reason the Federal Reserve aims for low, stable inflation rather than steadily falling prices.
What an Interest-Rate Cut Actually Does
The Federal Reserve does not set the price of eggs, gasoline or apartment rent. It sets a target range for the federal funds rate, the overnight rate banks charge one another.
That rate influences other borrowing costs throughout the economy.
When the Fed raises rates, mortgages, car loans, credit cards and business financing generally become more expensive. Households and companies tend to borrow and spend less. Weaker demand can eventually reduce pressure on businesses to keep raising prices.
When the Fed cuts rates, it is easing that restraint. Loans may become cheaper, businesses may invest more and consumers may feel more comfortable making large purchases. The goal is often to support employment and economic activity while keeping inflation under control.
None of this happens instantly. The Federal Reserve itself notes that the effects of monetary policy on inflation and employment are neither direct nor immediate.
A quarter-point cut also does not mean every consumer rate falls by a quarter point the next morning.
Mortgage rates, for example, depend partly on financial markets’ expectations about future inflation and future Fed decisions. Credit-card rates may adjust more directly, but they can remain extremely high.
Why Your Personal Inflation Rate May Feel Worse
National inflation numbers are averages. Your household does not buy the average basket of goods and services.
Someone who spends heavily on gasoline may feel a much larger squeeze when energy prices jump. A renter facing a new lease may experience housing inflation all at once. A family paying for child care, medical treatment or college may face price changes that look nothing like the national headline.
The Bureau of Labor Statistics explicitly warns that the published average may not match any one person’s experience.
That does not mean the data are false. It means millions of households have different budgets.
It also explains why improving inflation statistics can feel disconnected from ordinary life. People do not experience inflation as a percentage in a report. They experience it as the difference between what $100 bought then and what it buys now.
What Relief Would Really Look Like
For most households, meaningful relief does not require every price to return to an old level. It requires incomes to catch up and future price increases to become modest and predictable.
Lower borrowing costs can help around the edges. A less expensive car loan or home-equity line matters. A healthier job market matters more. Wage growth that consistently exceeds inflation matters most of all.
Some individual prices will fall. Gasoline, used cars, airfare and food categories often move in both directions. Competition, productivity improvements and repaired supply chains can also lower costs in particular industries.
But there is no single lever in Washington that resets the economy to 2019 prices.
The Federal Reserve’s job is less satisfying and more realistic: prevent today’s high prices from becoming tomorrow’s rapidly rising prices while trying not to damage employment in the process.
An interest-rate cut can make the road ahead easier.
It cannot take us backward.